Market overview and industry significance of the Longitudinal Joint Sealant Market
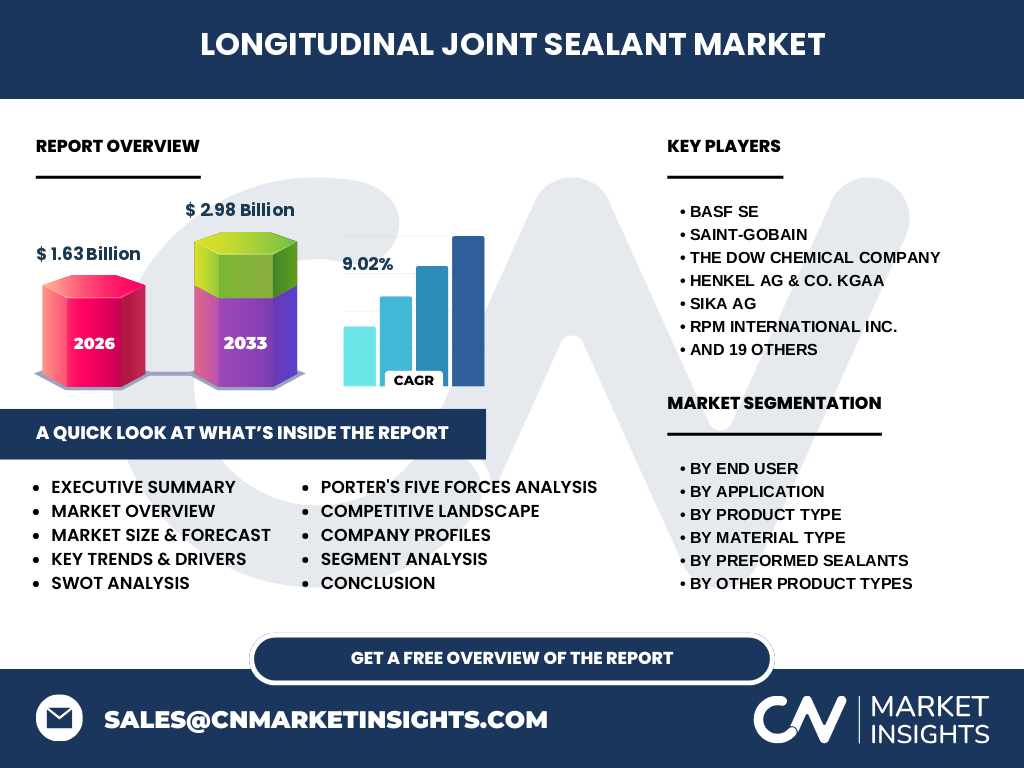
Our analysis indicates that the Longitudinal Joint Sealant Market stands at $1.63 Billion in 2026, serving as a critical defense mechanism against moisture infiltration in asphalt pavements. Utilizing raw materials like polymer-modified bitumen and polyurethane, these sealants prevent premature raveling and thermal cracking along lane joints. Regulatory bodies such as the Federal Highway Administration mandate strict joint integrity standards, elevating these formulations from basic maintenance supplies to essential infrastructure preservation assets.
What core factors act as market drivers, restraints, challenges, and opportunities in the Longitudinal Joint Sealant Market?
The market is propelled by aggressive federal transportation spending and the deterioration of aging highway networks. However, raw material volatility involving petroleum derivatives creates severe cost pressures for manufacturers like Crafco Inc. and Ergon Asphalt & Emulsions Inc. Opportunities thrive in eco-friendly bio-based sealants and polymer-modified bitumen, addressing stringent environmental compliance pushed by regional transportation agencies without sacrificing tensile strength or elasticity under extreme thermal cycling.
Emerging trends and growth patterns shaping the Longitudinal Joint Sealant Market
The shift toward sustainability has accelerated adoption of eco-friendly bio-based sealants and warm-mix compatible formulations. Industry leaders like W. R. Meadows Inc. and Maxwell Products Inc. are spearheading innovations that reduce carbon footprints during application. Our research highlights a surging preference for preformed thermoplastic rubber sealant strips, which minimize labor constraints and traffic disruption on high-volume commercial corridors and busy airport runways.
COVID-19 impact analysis and recovery trajectory
The pandemic initially disrupted supply chains and temporarily halted non-essential municipal paving projects, causing logistical bottlenecks for raw material distribution. Despite these headwinds, the market rebounded strongly as governments utilized infrastructure stimulus packages to accelerate delayed resurfacing programs. Companies adept at digital supply chain management successfully navigated labor shortages, ensuring continuous product flow to major highway expansion and bridge rehabilitation sites worldwide.
Competitive Benchmarking: Major players and strategic dynamics
The competitive landscape features a blend of diversified chemical giants and specialized pavement preservation specialists. Enterprises like BASF SE, The Dow Chemical Company, and Sika AG leverage robust R&D budgets to dominate high-end silicone and polyurethane segments. Meanwhile, niche players such as Crafco Inc. and Maxwell Products Inc. secure regional dominance through localized distribution networks and specialized rubberized asphalt sealants tailored to specific climatic demands.
Executive Summary: High-level synthesis of key findings
Our comprehensive evaluation confirms that the Longitudinal Joint Sealant Market is poised for remarkable expansion, scaling from $1.63 Billion in 2026 to $2.98 Billion by 2033 at a robust 9.02% CAGR. Strategic positioning around eco-friendly bio-based sealants and advanced polymer-modified bitumen will dictate market winners. Stakeholders must prioritize supply chain resilience and regulatory compliance to capitalize on accelerating global infrastructure modernization initiatives.
Market forecast trajectory from 2027 to 2033
Driven by compounding investments in smart transportation networks and rigorous pavement longevity mandates, the market will expand from $2.98 Billion by 2033 following a stellar 9.02% CAGR from its $1.63 Billion baseline in 2026. Infrastructure and highway applications will capture the lion's share of this growth, supported by sustained public-private partnerships aimed at reducing life-cycle maintenance costs for aging interstate systems and vital bridge decks.
Segmentation analysis across applications, products, and materials
The market divides across diverse categories: End Users (Infrastructure, Commercial, Residential, Other End Users); Applications (Highways, Airport Runways, Parking Lots, Bridges, Other Applications); Product Types (Hot-Applied Sealants including Bitumen Based, Polymer Modified Bitumen, Rubberized Asphalt, and Thermoplastic Sealants; Cold-Applied Sealants including Acrylic, Silicone, Polyurethane, and Emulsions; Preformed Sealants including Silicone Strips, Thermoplastic Rubber Strips, Bituminous Sheets, and Compression Profiles; plus Hybrid, Waterborne, Eco-Friendly Bio-Based, and Epoxy variants); and Material Types (Polyurethane, Silicone, Asphalt, Polysulfide, and Other Material Types).
Regional market analysis and geographic performance distribution
Geographic performance is heavily influenced by regional climate extremes and local transportation funding policies. North America commands significant market share due to extensive highway networks and rigorous Department of Transportation standards. Europe follows closely, driven by stringent environmental directives favoring low-VOC and bio-based formulations. Meanwhile, Asia-Pacific represents the fastest-growing regional market, fueled by massive urbanization waves and rapid highway construction in emerging economies.
In-depth regional review of key high-potential markets
North America remains a mature yet highly lucrative arena, where state DOT specifications dictate rigorous performance standards for hot-applied rubberized asphalt. In contrast, the Asia-Pacific region demonstrates explosive growth driven by arterial road expansions in rapidly industrializing nations. European markets prioritize sustainable construction, creating high-demand pockets for waterborne and eco-friendly bio-based sealants that meet strict EU environmental mandates.
Company profiles and strategic positioning of leading market participants
Market leaders employ distinct differentiation strategies. BASF SE and The Dow Chemical Company focus on advanced chemical formulations and global distribution muscle. Specialty manufacturers like Crafco Inc. and Ergon Asphalt & Emulsions Inc. anchor their competitive edge in tailored pavement preservation solutions. Meanwhile, innovators such as Sika AG and RPM International Inc. leverage targeted acquisitions to expand their product portfolios across both hot-applied and cold-applied sealant categories.
Porter's Five Forces analysis of the competitive landscape
The industry exhibits moderate-to-high rivalry driven by established chemical conglomerates and nimble regional blenders. Supplier power remains elevated due to raw material dependencies on petrochemical derivatives. Buyer power is counterbalanced by strict regulatory performance specifications that discourage cheap, unverified alternatives. The threat of substitutes is low given the specialized engineering requirements of longitudinal highway joints, while entry barriers remain moderately high due to rigorous qualification testing.
SWOT analysis of the Longitudinal Joint Sealant Market
Strengths include proven efficacy in extending pavement life and robust regulatory backing. Weaknesses involve vulnerability to crude oil price fluctuations affecting bitumen and polymer feedstock. Opportunities lie in emerging eco-friendly bio-based formulations and expanding infrastructure outlays in developing regions. Threats stem from severe supply chain disruptions and stringent environmental regulations targeting volatile organic compounds in traditional solvent-based products.
Value chain analysis from raw materials to end-users
The value chain initiates with upstream petroleum refiners and specialty chemical producers supplying raw polymers, bitumen, and silicone bases. Midstream participants—including major blenders like Crafco Inc., W. R. Meadows Inc., and SealMaster LP—compound these materials into specialized hot-applied and cold-applied formulations. Downstream distribution occurs via direct B2B sales to contractors, specialized distributors, and online retail channels, ultimately serving public works departments and commercial paving contractors.
Investment insights and strategic high-potential areas
Our analysis indicates that capital allocation should prioritize R&D in eco-friendly bio-based sealants and high-durability polymer-modified bitumen. Investors should target regional distributors and manufacturers capable of navigating localized environmental mandates. Companies possessing proprietary waterborne or hybrid formulations are exceptionally well-positioned to capture market share as municipal agencies increasingly penalize high-VOC products.
Conclusion and key strategic takeaways
The Longitudinal Joint Sealant Market offers compelling growth, advancing from $1.63 Billion in 2026 to $2.98 Billion by 2033 at a 9.02% CAGR. Success hinges on balancing product performance with sustainability demands. Organizations that invest in bio-based innovations and fortify their distribution channels will successfully outperform competitors in this rapidly modernizing sector.
Research methodology and baseline estimation triangulation
Baseline market estimates are established through rigorous triangulation combining trade registry data, customs import-export statistics, and exhaustive primary stakeholder interviews with c-suite executives across top market participants like Sika AG, Henkel AG & Co. KGaA, and Tremco Incorporated. Secondary macroeconomic indicators, including national highway construction budgets and regional asphalt production volumes, are cross-referenced to validate market sizing and forecast models.
Scope of the report, coverage parameters, and analytical limitations
This report encompasses a comprehensive global evaluation of the Longitudinal Joint Sealant Market across specified product, material, application, end-user, and distribution segments. While our model utilizes robust econometric forecasting and primary industry validation, limitations include unforeseen macroeconomic policy shifts, sudden geopolitical disruptions impacting chemical feedstocks, and localized municipal budget reallocations.
Recent developments, strategic partnerships, and product launches
Recent industry momentum is characterized by aggressive sustainability-focused product launches and strategic cross-sector partnerships. Key market players are investing heavily in advanced manufacturing lines for preformed thermoplastic rubber sealant strips and eco-friendly bio-based sealants. Furthermore, targeted acquisitions by firms like RPM International Inc. and Sika AG underscore a broader industry push to consolidate regional distribution networks and expand proprietary product portfolios.